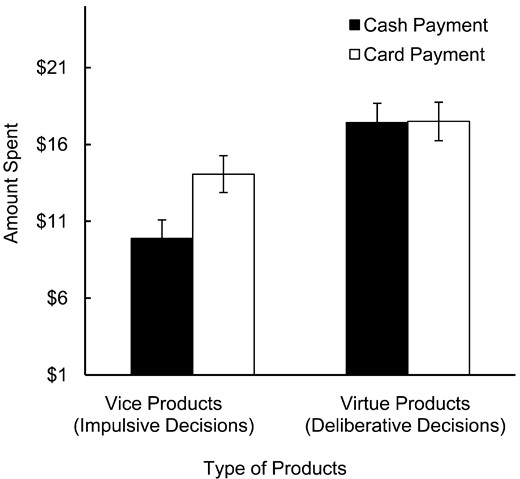
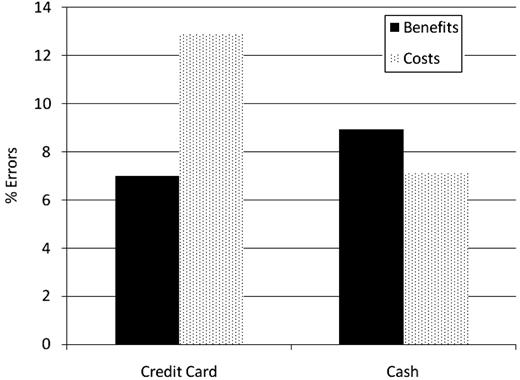
Abstract. Some food items that are commonly considered unhealthy also tend to elicit impulsive responses. The pain of paying in cash can curb impulsive urg
Credit Cards as Lifestyle Facilitators
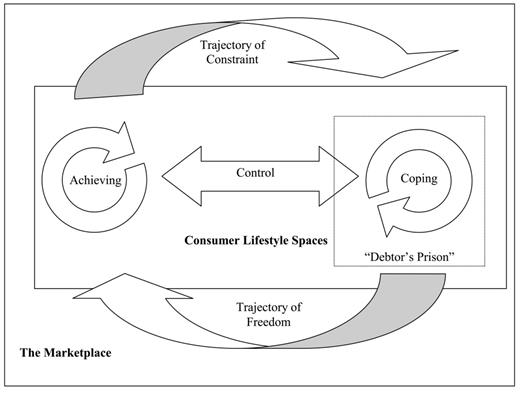
Abstract. Credit cards are an increasingly essential technology, but they carry with them the paradoxical capacity to propel consumers along lifestyle traj
Time to Cut Up Those Debit Cards? Effect of Payment Mode on Willingness to Spend
Financial industry data indicate that consumers increasingly prefer debit cards over credit cards, especially as a means of enforcing financial self-discipline. Given prior research suggesting that credit cards act as spending facilitating stimuli, this move toward reduced credit card use would appear to be in the right direction. Ironically, however, the same logos that were implicated in facilitating spending with credit cards are the logos that appear on debit cards. In what should serve as an eye-opener to consumers, it is found that exposure to debit card logos does result in an increased willingness to spend, similar to credit cards.
A Mega-Replication of the Effect of Cash Versus Card Payment on Pain of Paying: Magnitude, Behavioral Outcomes, and Moderators
Abstract We revisit the widely accepted finding that paying with cash is more painful than paying with card by conducting the first systematic mega-replication (including 13 large-scale preregistered replications; a total of 32,371 participants, 65 products, and 57 price points ranging from $1.09 to $400). The aggregate evidence reveals four insights: (1) leveraging a broad set of established paradigms, we replicate the finding that paying with cash is more psychologically painful than paying with card, even among today’s consumers who own multiple cards, digital wallets, and virtual currencies; (2) comparing two outcome variables—amount spent and willingness-to-pay (WTP), we find a more reliable and larger overall direct effect of payment method on amount spent than on WTP; (3) these direct effects of payment method on outcome variables are mediated by pain of paying; (4) the mode-of-payment effect on pain of paying (and thereby on outcome variables) is moderated by individual differences, particularly the relative frequency of using cash versus card. We outline actionable guidance and future directions for researchers and practitioners interested in examining mode-of-payment effects, and discuss the value of and suitable approaches for future theory-driven large-scale replications.

Credit Cards as Spending Facilitating Stimuli: A Conditioning Interpretation
Abstract. Four experiments and one study were conducted to test the hypothesis that stimuli associated with spending can elicit spending responses. In all
Purchase Justifiability Drives Payment Choice: Consumers Pay with Card to Remember and Cash to Forget
AbstractAlthough consumers often have multiple payment methods at their fingertips, such as cash and credit/debit cards, prior research is silent on how consumers choose between them. We home in on a key element of purchase—purchase justifiability—that affects how consumers choose to pay. Analysis of 118,042 real-world purchases and six experiments reveals that when consumers are motivated to forget (vs. remember) a purchase because they see it as difficult (vs. easy) to justify, they have an increased preference to pay with cash (vs. card) because cards create a “paper/electronic trail” that aids memory retrieval. These payment preferences are strongest among consumers most likely to recall/track their card spending, and manifest only when card expenses are trackable. We reconcile our results with the classic effect of payment method on pain of paying and discuss implications for merchants and for financial institutions designing payment methods of the future.

Yielding to Temptation: Self‐Control Failure, Impulsive Purchasing, and Consumer Behavior
Abstract. Self-control is a promising concept for consumer research, and self-control failure may be an important cause of impulsive purchasing. Three caus
Differences in Consumer Purchase Behavior by Credit Card Payment System
Abstract. A conceptualization of the relationships between alternative payment systems and various environmental and behavioral variables, which may serve
Payment Rewards and Credit Card Debt: Experimental Evidence
We report on a controlled laboratory experiment in which participants make consumption, saving, and credit card repayment decisions when credit card purchases e

Managing Mental Accounts: Payment Cards and Consumption Expenditures
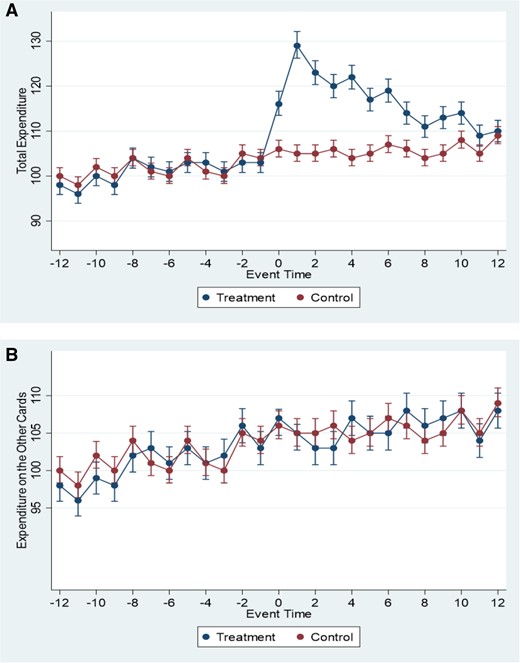
Does mental accounting matter for total consumption expenditures? We exploit a unique setting in which individuals exogenously received a new credit card, without requesting one. Using random variation in the time of receipt we show that individuals temporarily increase total consumption expenditure by making purchases with the new card without reducing spending on the others. We do not observe a corresponding increase in indebtedness. Total consumption expenditure rises even for the least liquidity-constrained individuals. The evidence is consistent with consumers treating methods of payment as nonfungible budget categories, as suggested by models of mental accounting and narrow bracketing.
“Repayment-by-Purchase” Increases Consumer Debt Repayment
This article tests the effect of a novel credit card payment format—repayment-by-purchase—on consumers’ payments toward credit card debt. In contrast to typical balance repayment, where consumers make repayments relative to a total amount owed, repayment-by-purchase prompts consumers to select items (e.g., a Starbucks coffee) or categories of purchase (e.g., restaurant and café purchases) and to make payments toward their related debt. A field experiment first suggests that customers who opted into repayment-by-purchase paid 12.18% more toward their statement balance than a control group. Subsequently, five lab experiments show that consumers repaying-by-purchase increase repayment by an average of 22.47% over typical balance repayment. Process evidence suggests that these differences may be driven by repayment-by-purchase's power to increase purchase salience, which in turns increases perceptions of progress toward reducing debt. Consistent with this theory, the effect of repayment-by-purchase on bill repayment emerges regardless of whether consumers repay durable versus nondurable goods, and for specific items or categories of purchases, as long as the bill uses labels that are concrete enough to raise past purchase salience.

Do Payment Mechanisms Change the Way Consumers Perceive Products?
Abstract. Do payment mechanisms change the way consumers perceive products? We argue that consumers for whom credit cards (cash) have been primed focus mor
Always Leave Home Without It: A Further Investigation of the Credit-Card Effect on Willingness to Pay
In studies involving genuine transactions of potentially high value we show that willingness-to-pay can be increased when customers are instructed to use a credit card rather than cash. The effect may be large (up to 100%) and it appears unlikely that it arises due solely to liquidity constraints. In addition to demonstrating the effect, we provide a methodology for detecting it, and our findings suggest a source of variance to test alternative explanations.
Managing Mental Accounts: Payment Cards and Consumption Expenditures
Abstract Does mental accounting matter for total consumption expenditures? We exploit a unique setting in which individuals exogenously receive a new payment card, without requesting one. Using random variation in the time of receipt, we show that individuals temporarily increase total consumption expenditure by making purchases with the new card without reducing spending on the others. We do not observe a corresponding increase in indebtedness. Total consumption expenditure rises even for the least liquidity-constrained individuals. The evidence is consistent with consumers treating methods of payment as nonfungible budget categories, as suggested by models of mental accounting and narrow bracketing.
Rewards and Misperceived Spending: Experimental Evidence from Credit Cards
Using proprietary data, a survey, and an experiment with a major bank in China, this paper studies how credit card rewards affect perceived and actual consumer
Overconfidence and the Credit Card Debt Puzzle
This article investigates the credit card debt puzzle. Simultaneously holding credit card debt and liquid assets is puzzling given the sizeable difference between interest rates of debt and assets. However, this behavior is common—about 31% of households in the 2016 Survey of Consumer Finances. The cost of co-holding may be justified if consumers anticipate future restrictions in credit or if they need to maintain liquidity. Other existing explanations for co-holding include impulsive spending and low financial literacy. This research reveals a new explanation for the credit card debt puzzle: consumers’ overconfidence of their financial knowledge. Using a Coarsened Exact Matching method, we found that overconfident consumers were 20%–40% more likely to co-hold credit card debt and liquid assets.
How Are SNAP Benefits Spent? Evidence from a Retail Panel
We use a novel retail panel with detailed transaction records to study the effect of the Supplemental Nutrition Assistance Program (SNAP) on house-hold spending. We use administrative data to motivate three approaches to causal inference. The marginal propensity to consume SNAP-eligible food (MPCF) out of SNAP benefits is 0.5 to 0.6. The MPCF out of cash is much smaller. These patterns obtain even for households for whom SNAP benefits are economically equivalent to cash because their benefits are below their food spending. Using a semiparametric framework, we reject the hypothesis that households respect the fungibility of money. A model with mental accounting can match the facts.