


The standard model of labor is one in which individuals trade their time and energy in return for monetary rewards. Building on Fiske's relational theory (1992), we propose that there are two types of markets that determine relationships between effort and payment: monetary and social. We hypothesize that monetary markets are highly sensitive to the magnitude of compensation, whereas social markets are not. This perspective can shed light on the well-established observation that people sometimes expend more effort in exchange for no payment (a social market) than they expend when they receive low payment (a monetary market). Three experiments support these ideas. The experimental evidence also demonstrates that mixed markets (markets that include aspects of both social and monetary markets) more closely resemble monetary than social markets.
Small Probabilistic Discounts Stimulate Spending: Pain of Paying in Price Promotions
AbstractWe find that small probabilistic price promotions effectively stimulate demand, even more so than comparable fixed price promotions (e.g., “1% chance it’s free” vs. “1% off,” respectively), because they more effectively reduce the pain of paying. In three field experiments at a grocer, we exogenously and endogenously manipulated the salience of pain of paying via elicitation timing (e.g., at entrance or checkout) and payment method (i.e., cash/debit cards or credit cards). This modulated the attractiveness of probabilistic discounts and their ability to stimulate spending. Shoppers paying with cash or debit cards, for example, spent 54% more if they received a 1% probabilistic discount than a 1% fixed discount (experiment 2). A fourth experiment showed that consumers’ sensitivity to pain of paying modulates the greater comparative efficacy of small probabilistic than fixed discounts. More broadly, the results elucidate a novel affective route through which price promotions stimulate demand––pain of paying.

Pain of Paying? — A Metaphor Gone Literal: Evidence from Neural and Behavioral Science
How do individuals consider the price of a good when making purchase decisions? Standard economic theories assume an analytical process: Individuals consider th

Cut me some slack! How perceptions of financial slack influence pain of payment
Abstract Consumers often experience pain of payment, a tug of negative affect that holds back their spending. While the literature has long viewed pain of payment as self‐regulatory in nature, it has left the dynamics of self‐regulation that lead to the pain of paying largely unaddressed. In self‐regulation, affect arises when people move away from a goal they hold. Thus, understanding the specific goals that people consider when making a payment can help us better predict when pain of payment will arise. We propose that people have a goal to maintain financial slack, and that violating this goal contributes to pain of payment. Thus, people experience more pain of payment when the goal to maintain financial slack is stronger or when it is particularly salient that a purchase entails losing financial slack. Critically, subjective changes in financial slack are not equivalent to objective changes in wealth, altering pain of payment for economically equivalent trades. This research contributes to the existing literature by identifying a novel antecedent to the pain of payment. It additionally expands our understanding of people's preferences between payment systems. Finally, it offers guidance to practitioners who wish to minimize pain of payment among their consumers.

The Impact of Payment Frequency on Consumer Spending and Subjective Wealth Perceptions
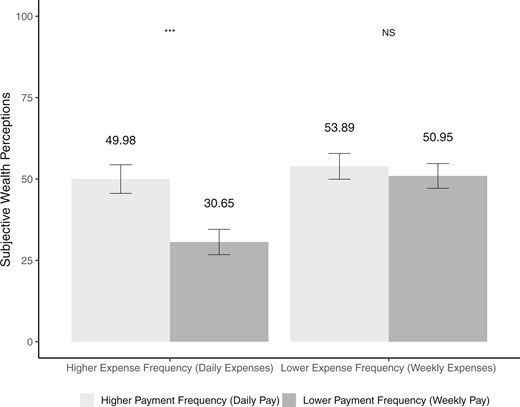
Abstract Payment frequency is a fundamental yet underexplored feature of consumers’ finances. As higher payment frequencies are becoming more prevalent, consumers are receiving more frequent yet smaller paychecks. An analysis of income and expenditure data of over 30,000 consumers from a financial services provider demonstrates a naturally occurring relationship between higher payment frequencies and increased spending. A series of lab studies support this finding, providing causal evidence that higher (vs. lower) payment frequencies increase spending. The effect of payment frequency on spending is driven by changes in consumers’ subjective wealth perceptions. Specifically, higher payment frequencies reduce consumers’ uncertainty in predicting whether they will have enough resources throughout a period, increasing their subjective wealth perceptions. As such, situational factors that reduce prediction uncertainty for those paid less frequently (e.g., the timing of consumers’ expenses, income levels) moderate the impact of payment frequency. The effects of payment frequency on subjective wealth and spending can occur even when objective wealth favors those with lower payment frequencies. More broadly, the current work underscores a need to understand how timing variations in consumers’ income impact their perceptions, behaviors, and general well-being.
Monopoly money: The effect of payment coupling and form on spending behavior.
The Hedonics of Debt
Psychologists and economists often discuss the “pain” of paying for our purchases. Four experiments examine how people evaluate prospective debt payments, analyzing how different features of a loan (down payment, final payment, duration, monthly payments) affect willingness to accept the loan. Akin to previous findings on physical pain, participants exhibited duration neglect and over-weighted final moments. However, participants also focused heavily on the monthly or average payment (unlike in retrospective studies of physical pain where only peak-end moments seem to count). In Experiment 2, participants’ willingness to accept the loan was not significantly diminished by making it more expensive through keeping the same monthly payment but extending the length of the loan by 40 percent (evincing duration neglect). Further, in Experiments 3 and 4, we show that participants increased their willingness to buy if loans were made longer and more expensive by adding smaller, less “painful” payments to the end.

The Effect of Payment Transparency on Consumption: Quasi-Experiments from the Field
Recent research suggests that the method of making a payment can influence the willingness to pay and consumption behavior. In this manuscript, we argue that payment mechanisms differ from each other along the dimensions of transparency, and that the degree of transparency correlates positively with the pain of paying using the mechanism, and negatively with consumption and spending. We replicate previous experimental results using quasi-experiments from the field, and find that the lower the payment transparency, the greater is the consumption. However, this effect is weak for products whose consumption rates are inflexible.
Monetary incentives, what are they good for?
This paper is a critical reflection on the use of monetary incentives in economic experiments. The argument is that incentives have their effect through their influence on one or more of three fact...

The Effects of Financial Incentives in Experiments: A Review and Capital-Labor-Production Framework
We review 74 experiments with no, low, or high performance-based financial incentives. The modal result has no effect on mean performance (though variance is usually reduced by higher payment). Higher incentive does improve performance often, typically judgment tasks that are responsive to better effort. Incentives also reduce “presentation” effects (e.g., generosity and risk-seeking). Incentive effects are comparable to effects of other variables, particularly “cognitive capital” and task “production” demands, and interact with those variables, so a narrow-minded focus on incentives alone is misguided. We also note that no replicated study has made rationality violations disappear purely by raising incentives.
The Red and the Black: Mental Accounting of Savings and Debt
In the standard economic account of consumer behavior the cost of a purchase takes the form of a reduction in future utility when expenditures that otherwise could have been made are forgone. The reality of consumer hedonics is different. When people make purchases, they often experience an immediate pain of paying, which can undermine the pleasure derived from consumption. The ticking of the taxi meter, for example, reduces one's pleasure from the ride. We propose a “double-entry” mental accounting theory that describes the nature of these reciprocal interactions between the pleasure of consumption and the pain of paying and draws out their implications for consumer behavior and hedonics. A central assumption of the model, which we call prospective accounting, is that consumption that has already been paid for can be enjoyed as if it were free and that the pain associated with payments made prior to consumption (but not after) is buffered by thoughts of the benefits that the payments will finance. Another important concept is coupling, which refers to the degree to which consumption calls to mind thoughts of payment, and vice versa. Some financing methods, such as credit cards, tend to weaken coupling, whereas others, such as cash payment, produce tight coupling. Our model makes a variety of predictions that are at variance with economic formulations. Contrary to the standard prediction that people will finance purchases to minimize the present value of payments, our model predicts strong debt aversion—that they should prefer to prepay for consumption or to get paid for work after it is performed. Such pay-before sequences confer hedonic benefits because consumption can be enjoyed without thinking about the need to pay for it in the future. Likewise, when paying beforehand, the pain of paying is mitigated by thoughts of future consumption benefits. Contrary to the economic prediction that consumers should prefer to pay, at the margin, for what they consume, our model predicts that consumers will find it less painful to pay for, and hence will prefer, flat-rate pricing schemes such as unlimited Internet access at a fixed monthly price, even if it involves paying more for the same usage. Other predictions concern spending patterns with cash, charge, or credit cards, and preferences for the earmarking of purchases. We test these predictions in a series of surveys and in a conjoint-like analysis that pitted our double-entry mental accounting model against a standard discounting formulation and another benchmark that did not incorporate hedonic interactions between consumption and payments. Our model provides a better fit of the data for 60% of the subjects; the discounting formulation provides a better fit for only 29% of the subjects (even when allowing for positive and negative discount rates). The pain of paying, we argue, plays an important role in consumer self-regulation, but is hedonically costly. From a hedonic perspective the ideal situation is one in which payments are tightly coupled to consumption (so that paying evokes thoughts about the benefits being financed) but consumption is decoupled from payments (so that consumption does not evoke thoughts about payment). From an efficiency perspective, however, it is important for consumers to be aware of what they are paying for consumption. This creates a tension between hedonic efficiency and what we call decision efficiency. Various institutional arrangements, such as financing of public parks through taxes or usage fees, play into this tradeoff. A producer developing a pricing structure for their product or service should be aware of these two conflicting objectives, and should try to devise a structure that reconciles them.

Pay Enough or Don't Pay at All*
Abstract. Economists usually assume that monetary incentives improve performance, and psychologists claim that the opposite may happen. We present and disc

Intra-Household Frictions, Anchoring, and the Credit Card Debt Puzzle
Abstract I study how intra-household frictions and anchoring contribute to the credit card debt puzzle, the co-holding of high-cost debt, and low-yield liquid assets. First, I find couples co-hold 42% more as units than as individuals relative to income. Moreover, in a natural experiment, couples do not cooperate to reduce high-cost debt, suggesting that intra-household frictions contribute to co-holding. Second, I find individuals who regularly make credit card debt payments equal to or near the minimum account for 59% of individual co-holding. The evidence suggests anchoring to the minimum payment contributes to co-holding via these low payments.
The pain of payment: A review and research agenda
Abstract Pain of payment is the negative psychological affect consumers experience when they become cognizant that they have lost a certain amount of their financial resources (immediate pain) or when they become aware that they will or may lose a certain amount of their financial resources in the future (anticipated pain). Pain of payment plays a significant role in consumer decision making and has attracted substantial scholarly interest in recent years. In this article, we conduct a systematic literature review of the existing work on pain of payment. We advance theory in the field by proposing a new organizing framework that summarizes the antecedents, moderators, and consequences of pain of payment. Furthermore, we provide a formal definition of pain of payment that encompasses all facets of this construct. Subsequently, we identify knowledge gaps and outline research questions that could be explored to improve our understanding of this construct and advance consumer psychology.

Payment Depreciation: the Behavioral Effects of Temporally Separating Payments From Consumption
Abstract. Research suggests that individuals mentally track the costs and benefits of a consumer transaction for the purpose of reconciling those costs and
Tightwads and spendthrifts: An interdisciplinary review
Consumers rely on a “pain of paying” to help deter their spending. While this is beneficial for some consumers, others experience levels of pain that create problems. “Tightwads” experience too much pain when considering spending and therefore spend less than they would ideally like to spend. By contrast, “spendthrifts” experience too little pain and therefore spend more than they would ideally like to spend. Neither are happy with how they handle money. In the decade since the tightwad‐spendthrift construct was introduced, much has been learned about what it is and is not (e.g., frugality, greed), what contextual factors are likely to reduce its importance, how it plays a role within romantic relationships, and when it might first emerge in childhood. This paper reviews the wide range of interdisciplinary research relevant to the tightwad‐spendthrift construct and proposes several directions for new research.

A Mega-Replication of the Effect of Cash Versus Card Payment on Pain of Paying: Magnitude, Behavioral Outcomes, and Moderators
Abstract We revisit the widely accepted finding that paying with cash is more painful than paying with card by conducting the first systematic mega-replication (including 13 large-scale preregistered replications; a total of 32,371 participants, 65 products, and 57 price points ranging from $1.09 to $400). The aggregate evidence reveals four insights: (1) leveraging a broad set of established paradigms, we replicate the finding that paying with cash is more psychologically painful than paying with card, even among today’s consumers who own multiple cards, digital wallets, and virtual currencies; (2) comparing two outcome variables—amount spent and willingness-to-pay (WTP), we find a more reliable and larger overall direct effect of payment method on amount spent than on WTP; (3) these direct effects of payment method on outcome variables are mediated by pain of paying; (4) the mode-of-payment effect on pain of paying (and thereby on outcome variables) is moderated by individual differences, particularly the relative frequency of using cash versus card. We outline actionable guidance and future directions for researchers and practitioners interested in examining mode-of-payment effects, and discuss the value of and suitable approaches for future theory-driven large-scale replications.
