


We study the impact of a financial education program on portfolio choices in a setting that allows us to examine both participation decisions and differences in program benefits across individuals. We directly elicit willingness to pay for financial education and show that individuals with higher financial literacy, greater confidence in applying new knowledge, and higher expected returns are willing to pay more. Using incentivized portfolio allocation tasks, we develop outcome measures tailored to individual risk preferences and show that financial education improves decision quality along these dimensions. The program increases the share of participants who experience an improvement by 20 percentage points, corresponding to average gains of 3.2 percentage points of initial wealth. Individuals with the highest willingness to participate benefit disproportionately from the program, with important implications for the design and evaluation of financial education initiatives. By isolating a specific investment skill in a setting with voluntary participation, our design sheds light on how selection into financial education shapes measured program effects and informs the assessment of broader workplace and public training programs. This paper was accepted by Marie Claire Villeval, behavioral economics and decision analysis. Funding: The authors thank the Pension Research Council of Wharton School at the University of Pennsylvania, as well as the Retirement and Savings Institute at HEC Montréal, for generous research funding. Supplemental Material: The online appendices and data files are available at https://doi.org/10.1287/mnsc.2024.08268 .
5: Behavioural biases in personal finance
Behavioural economics merges psychology and economics to explore systematic deviations in financial decision-making from traditional economic models. This chapter examines key biases such as mental accounting, present bias, planning fallacy, and misunderstanding of risk, which influence spending, saving, investing, and insuring decisions. Demonstrating the interplay of cognitive biases and heuristics highlights why individuals make suboptimal choices despite financial literacy and resource capacity. Strategies like goal-setting, commitment devices, and education interventions are evaluated, focusing on their limitations and potential for addressing these biases. The chapter concludes by emphasising the need for systemic changes, such as policy-level interventions and financial regulation, to complement behavioural interventions and address structural barriers to better financial decisions. Future research directions are suggested, including tailoring interventions, exploring technology's role, and integrating systemic solutions to support sustainable financial well-being.
Financial Literacy, Financial Education, and Downstream Financial Behaviors
Policy makers have embraced financial education as a necessary antidote to the increasing complexity of consumers' financial decisions over the last generation. We conduct a meta-analysis of the relationship of financial literacy and of financial education to financial behaviors in 168 papers covering 201 prior studies. We find that interventions to improve financial literacy explain only 0.1% of the variance in financial behaviors studied, with weaker effects in low-income samples. Like other education, financial education decays over time; even large interventions with many hours of instruction have negligible effects on behavior 20 months or more from the time of intervention. Correlational studies that measure financial literacy find stronger associations with financial behaviors. We conduct three empirical studies, and we find that the partial effects of financial literacy diminish dramatically when one controls for psychological traits that have been omitted in prior research or when one uses an instrument for financial literacy to control for omitted variables. Financial education as studied to date has serious limitations that have been masked by the apparently larger effects in correlational studies. We envisage a reduced role for financial education that is not elaborated or acted upon soon afterward. We suggest a real but narrower role for “just-in-time” financial education tied to specific behaviors it intends to help. We conclude with a discussion of the characteristics of behaviors that might affect the policy maker's mix of financial education, choice architecture, and regulation as tools to help consumer financial behavior. This paper was accepted by Uri Gneezy, behavioral economics.
The ABCs of Financial Education: Experimental Evidence on Attitudes, Behavior, and Cognitive Biases
This paper uses a large-scale field experiment in India to study attitudinal, behavioral, and cognitive constraints that can stymie the link between financial education and financial outcomes. The study complements financial education with (i) financial incentives on a financial literacy test to affect participant motivation, (ii) financial goal setting to provide a psychological nudge, and (iii) personalized financial counseling to enhance the intensity of treatment. The analysis finds no impact of financial incentives on learning but significant effects of both goal setting and counseling on real financial outcomes. These results identify important complements to financial education that can bridge the gap between financial knowledge and behavior change. Data and the online appendix are available at https://doi.org/10.1287/mnsc.2017.2819 . This paper was accepted by Amit Seru, finance.
The Financial Knowledge Scale: An Application of Item Response Theory to the Assessment of Financial Literacy
Despite increasing interest in and funding for financial literacy and financial education programs in the private and public sectors, the field of financial literacy still has a major obstacle to overcome: the lack of a widely disseminated measure of financial literacy, developed through rigorous psychometric analyses. In this article, we develop such a measure, focusing specifically on financial knowledge . Using item response theory (IRT), we analyze items from three national surveys, resulting in a psychometrically sound 20‐item financial knowledge scale. By using IRT, the current analysis uses individuals' answers to inform which questions to include in the scale in the first place, rather than simply confirming relationships between these answers and other financially relevant outcomes post hoc. Widespread use of this index and the continued use of modern psychometric techniques would allow for the comparison of financial knowledge, measured consistently and reliably, across studies, populations, and programs.

Household Finance
Household financial decisions are complex, interdependent, and heterogeneous, and central to the functioning of the financial system. We present an overview of the rapidly expanding literature on household finance (with some important exceptions) and suggest directions for future research. We begin with the theory and empirics of asset market participation and asset allocation over the life cycle. We then discuss household choices in insurance markets, trading behavior, decisions on retirement saving, and financial choices by retirees. We survey research on liabilities, including mortgage choice, refinancing, and default, and household behavior in unsecured credit markets, including credit cards and payday lending. We then connect the household to its social environment, including peer effects, cultural and hereditary factors, intra-household financial decision-making, financial literacy, cognition, and educational interventions. We also discuss literature on the provision and consumption of financial advice.
Behaviorally Informed Policies for Household Financial Decisionmaking
Low incomes, limited financial literacy, fraud, and deception are just a few of the many intractable economic and social factors that contribute to the financial difficulties that households face today. Addressing these issues directly is difficult and costly. But poor financial outcomes also result from systematic psychological tendencies, including imperfect optimization, biased judgments and preferences, and susceptibility to influence by the actions and opinions of others. Some of these psychological tendencies and the problems they cause may be countered by policies and interventions that are both low cost and scalable. We detail the ways that these behavioral factors contribute to consumers’ fiancial mistakes and suggest a set of interventions that the federal government, in its dual roles as regulator and employer, could feasibly test or implement to improve household financial outcomes in a variety of domains: retirement, short-term savings, debt management, the take-up of government benefits, and tax optimization.

Behavioral Impediments to Valuing Annuities: Complexity and Choice Bracketing
Abstract This paper examines two behavioral factors that diminish people's ability to value a lifetime income stream or annuity, drawing on a randomized experiment with about 4,000 adults in a U.S. nationally representative sample. We find that increasing the complexity of the annuity choice reduces respondents' ability to value the annuity, measured by the difference between the sell and buy values they assign to the annuity. When we limit narrow choice bracketing by inducing people to think first about how quickly or slowly to spend down assets in retirement, their ability to value an annuity increases.
The Credit Card Debt Puzzle: The Role of Preferences, Credit Access Risk, and Financial Literacy
Abstract. We use the 1979 National Longitudinal Survey of Youth to revisit what is termed the credit card debt puzzle: why consumers simultaneously co-hold high-interest credit card debt and low-interest assets that could be used to pay down this debt. Relative to individuals with no credit card debt but positive liquid assets, borrower-savers have very different perceptions of future credit access risk and use credit cards for precautionary motives. Moreover, changing perceptions about credit access risk are essential for predicting transitions among the two groups. Preferences and the composition of financial portfolios also play a role in these transitions.
Artificial intelligence and personal finance
Artificial intelligence (AI) is transforming how consumers access and use financial information, education and advice for personal financial decision making. While consumers’ increasing use of AI tools and AI-generated content for personal finance brings opportunities in terms of accessibility, personalisation and decision making, it also increases risks related to bias, hallucinations, commercial influence, data privacy and exclusion, with uncertain benefits on long-term financial well-being. This policy paper provides policymakers and stakeholders with an overview of current trends, opportunities and risks in the use of AI in personal finance and in the design and delivery of financial education. It also proposes a set of financial literacy competencies to support the use of AI in personal financial decision making.

Do people like financial nudges?
Do people like financial nudges? To answer that question we conducted a pre-registered survey presenting people with 36 hypothetical scenarios describing financial interventions. We varied levels of transparency (i.e., explaining how the interventions worked), framing (interventions framed in terms of spending, or saving), and ‘System’ (interventions could target either System 1 or System 2). Participants were a random sample of 2,100 people drawn from a representative Australian population. All financial interventions were tested across six dependent variables: approval, benefit, ethics, manipulation, the likelihood of use, as well as the likelihood of use if the intervention were to be proposed by a bank. Results indicate that people generally approve of financial interventions, rating them as neutral to positive across all dependent variables (except for manipulation, which was reverse coded). We find effects of framing and System. People have strong and significant preferences for System 2 interventions, and interventions framed in terms of savings. Transparency was not found to have a significant impact on how people rate financial interventions. Financial interventions continue to be rated positive, regardless of the messenger. Looking at demographics, we find that participants who were female, younger, living in metro areas and earning higher incomes were most likely to favor financial interventions, and this effect is especially strong for those aged under 45. We discuss the implications for these results as applied to the financial sector.

Liquidity Affects Job Choice: Evidence from Teach for America*
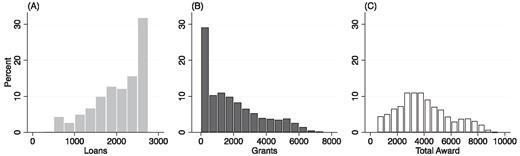
Abstract Can access to a few hundred dollars of liquidity affect the career choice of a recent college graduate? In a three-year field experiment with Teach For America (TFA), a prestigious teacher placement program, we randomly increase the financial packages offered to nearly 7,300 potential teachers who requested support for the transition into teaching. The first two years of the experiment reveal that although most applicants do not respond to a marginal $600 of grants or loans, those in the worst financial position respond by joining TFA at higher rates. We continue the experiment into the third year and self-replicate our results. For the highest-need applicants, an extra $600 in loans, $600 in grants, and $1,200 in grants increase the likelihood of joining TFA by 12.2, 11.4, and 17.1 percentage points (or 20.0%, 18.7%, and 28.1%), respectively. Additional grant and loan dollars are equally effective, suggesting a liquidity mechanism. A follow-up survey bolsters the liquidity story and also shows that those drawn into teaching would have otherwise worked in private-sector firms.
Temporal Reframing and Participation in a Savings Program: A Field Experiment
This study explores whether framing savings in more or less granular formats can increase sign-ups for a recurring deposit program in a FinTech environment. , A growing number of American workers are now freelancers and thus, responsible for their own retirement savings, yet they face psychological hurdles that hamper them from saving enough money for the long term. Although prior theory-derived interventions have been successful in addressing some of these obstacles, encouraging participation in saving programs is a challenging endeavor for policy makers and consumers alike. In a field setting, we test whether framing savings in more or less granular formats (for example, saving daily versus monthly) can encourage continued saving behavior through increasing the take up of a recurring deposit program. Among thousands of new users of a financial technology app, we find that framing deposits in daily amounts as opposed to monthly amounts quadruples the number of consumers who enroll. Furthermore, framing deposits in more granular terms reduced the participation gap between lower- and higher-income consumers: three times as many consumers in the highest rather than lowest income bracket participated in the program when it was framed as a $150 monthly deposit, but this difference in participation was eliminated when deposits were framed as $5 per day.

Personal Finance
Get the Business Insider take and compare the best savings accounts, best credit cards, best insurance policies, and more. Never feel like a financial outsider again.
Debt literacy, financial experiences, and overindebtedness
We analyze a national sample of Americans with respect to their debt literacy, financial experiences, and their judgments about the extent of their indebtedness. Debt literacy is a component of broader financial understanding that measures knowledge about debt and self-assessed financial knowledge. Financial experiences are the participants’ reported experiences with traditional borrowing, alternative borrowing, and investing. Overindebtedness is a self-reported measure. Debt literacy is low, with only about one-third of the population grasping the basics of interest compounding. Even after controlling for demographics, we find a relationship between debt literacy and both financial experiences and debt loads. Individuals with lower levels of debt literacy tend to transact in high-cost manners, incurring higher fees and using high-cost borrowing. We provide a rough estimate of the national implications of debt ignorance on credit card costs by consumers. Less knowledgeable individuals also report that their debt loads are excessive or that they are unable to judge their debt position.
The persistence of cognitive biases in financial decisions across economic groups
While economic inequality continues to rise within countries, efforts to address it have been largely ineffective, particularly those involving behavioral approaches. It is often implied but not tested that choice patterns among low-income individuals may be a factor impeding behavioral interventions aimed at improving upward economic mobility. To test this, we assessed rates of ten cognitive biases across nearly 5000 participants from 27 countries. Our analyses were primarily focused on 1458 individuals that were either low-income adults or individuals who grew up in disadvantaged households but had above-average financial well-being as adults, known as positive deviants. Using discrete and complex models, we find evidence of no differences within or between groups or countries. We therefore conclude that choices impeded by cognitive biases alone cannot explain why some individuals do not experience upward economic mobility. Policies must combine both behavioral and structural interventions to improve financial well-being across populations.

Prospect Theory, Mental Accounting, and Differences in Aggregated and Segregated Evaluation of Lottery Portfolios
If individuals have to evaluate a sequence of lotteries, their judgment is influenced by the presentation mode. Experimental studies have found significantly higher acceptance rates for a sequence of lotteries if the overall distribution was displayed instead of the set of lotteries itself. Mental accounting and loss aversion provide an easy and intuitive explanation for this phenomenon. In this paper we offer an explanation that incorporates further evaluation concepts of Prospect Theory. Our formal analysis of the difference in aggregated and segregated portfolio evaluation demonstrates that the higher attractiveness of the aggregated presentation mode is not a general phenomenon (as suggested in the literature) but depends on specific parameters of the lotteries. The theoretical findings are supported by an experimental study. In contrast to the existing evidence and in line with our theoretical results, we find for specific types of lotteries an even lower acceptance rate if the overall distribution is displayed.