


And are they fair?
You’ve Got Mail: A Randomized Field Experiment on Tax Evasion
We report from a large-scale randomized field experiment conducted on a unique sample of more than 15,000 taxpayers in Norway who were likely to have misreported their foreign income. By randomly manipulating a letter from the tax authorities, we cleanly identify that moral suasion and the perceived detection probability play a crucial role in shaping taxpayer behavior. The moral letter mainly works on the intensive margin, while the detection letter has a strong effect on the extensive margin. We further show that only the detection letter has long-term effects on tax compliance. This paper was accepted by Yan Chen, behavioral economics.

Yeah, We're Going to Have to Tax the Middle Class
Shaping Preferences with Pigouvian Taxes
A Pigouvian tax is a tax that is imposed to correct an externality, which arises when a person engages in behavior that harms others without their consent. Pigouvian taxes are popular among academics—with prominent economists and legal scholars arguing for their imposition on myriad goods and activities that harm third parties, like carbon emissions and alcohol. Policymakers have recently been receptive to at least some of these arguments as evidenced by taxes imposed on or proposed for a variety of externality-generating goods, including guns, plastic bags, and sugary drinks.The conventional economic rationale for Pigouvian taxes assumes that they affect behavior by increasing the prices of taxed goods and not by altering people’s underlying preferences for them. For example, a carbon tax reduces driving by making gasoline more expensive, but it otherwise leaves people’s desire to drive unchanged. This conclusion follows from the standard assumption in economics that people’s tastes and preferences are fixed and determined exogenously to public policy.Contrary to standard analysis, I argue that Pigouvian taxes can in fact shape preferences and that policymakers should consider using them for that purpose. A carbon tax, for instance, would not only make driving more expensive, it might also modify preferences such that people develop a taste for alternative modes of transportation—making driving less desirable, even if we ignore the increase in gas prices.I make an original contribution to the literature on Pigouvian taxes by explaining in detail the psychological mechanisms through which these taxes can alter preferences. I also argue that once we relax the assumption of fixed preferences, the already strong case for Pigouvian taxes often becomes even more compelling. Specifically, preference endogeneity means that the loss in consumer utility resulting from Pigouvian taxes will often be smaller than standard analysis suggests. Moreover, malleable preferences dramatically expand the potential scope for Pigouvian taxes and enhance their impact on behavior through a social multiplier effect that can make taxes more effective in achieving public policy goals than scholars have traditionally assumed. I illustrate these points in a variety of policy-relevant contexts, including environmental law, gun control, and public health policy.
I Moved to New York to Pay More in Taxes—and I’m Glad I Did
I wasn’t getting the bang for my buck in my red-state redoubt. But if I hadn’t moved, I might never have found out how good it could get.

Who Pays? 7th Edition
Who Pays? is the only distributional analysis of tax systems in all 50 states and the District of Columbia. This comprehensive 7th edition of the report assesses the progressivity and regressivity of state tax systems by measuring effective state and local tax rates paid by all income groups.
Vermin Trials
AbstractFor 250 years insects and rodents accused of committing property crimes were tried as legal persons in French, Italian, and Swiss ecclesiastic courts under the same laws and according to the same procedures used to try actual persons. I argue that the Catholic Church used vermin trials to increase tithe revenues where tithe evasion threatened to erode them. Vermin trials achieved this by bolstering citizens’ belief in the validity of Church punishments for tithe evasion: estrangement from God through sin, excommunication, and anathema. Vermin trials permitted ecclesiastics to evidence their supernatural sanctions’ legitimacy by producing outcomes that supported those sanctions’ validity. These outcomes strengthened citizens’ belief that the Church’s imprecations were real, which allowed ecclesiastics to reclaim jeopardized tithe revenue.

Will Canada’s gas tax holiday drive up emissions and help the rich? | The Narwhal
The Carney government is keeping its tax off at gas pumps to help with the cost of living, but critics call it a subsidy for the oil and gas industry that won’t help those who need it most
Adjustment Costs, Firm Responses, and Micro vs. Macro Labor Supply Elasticities: Evidence from Danish Tax Records
Abstract. We show that the effects of taxes on labor supply are shaped by interactions between adjustment costs for workers and hours constraints set by fi

The Paradox of Redistribution and Strategies of Equality: Welfare State Institutions, Inequality, and Poverty in the Western Countries
Debates on how to reduce poverty and inequality have focused on two controversial questions: Should social policies be targeted to low-income groups or be universal? Should benefits be equal for all or earnings-related? Traditional arguments in favor of targeting and flat-rate benefits, focusing on the distribution of the money actually transferred, neglect three policy-relevant considerations: (1) The size of redistributive budgets is not fixed but reflects the structure of welfare state institutions. (2) A trade-off exists between the degree of low-income targeting and the size of redistributive budgets. (3) Outcomes of market-based distribution are often more unequal than those of earnings-related social insurance programs. We argue that social insurance institutions are of central importance for redistributive outcomes. Using new data, our comparative analyses of the effects of different institutional types of welfare states on poverty and inequality indicate that institutional differences lead to unexpected outcomes and generate the paradox of redistribution: The more we target benefits at the poor and the more concerned we are with creating equality via equal public transfers to all, the less likely we are to reduce poverty and inequality.
Why Religion, Not Income, Predicts the American Vote
Inside the data that shows socioeconomic status barely matters once you know someone’s religious tradition.
Why We Need to Confront the Billionaires’ Paradise
The UBS/PwC report on the “new Gilded Age” of the billionaire class, and the Paradise Papers reveal ways corporations and the ultrawealthy avoid taxes.
Who Pays For Your Rewards? Redistribution in the Credit Card Market
The Federal Reserve Board of Governors in Washington DC.
La taxation des transactions financières : une opportunité à réinventer
Les débats autour de la taxation des transactions financières passent peut-être à côté de l’essentiel. Alors qu’on a tendance à se focaliser sur son taux, c’est en changeant les modalités de collecte qu’on pourrait améliorer son rendement.
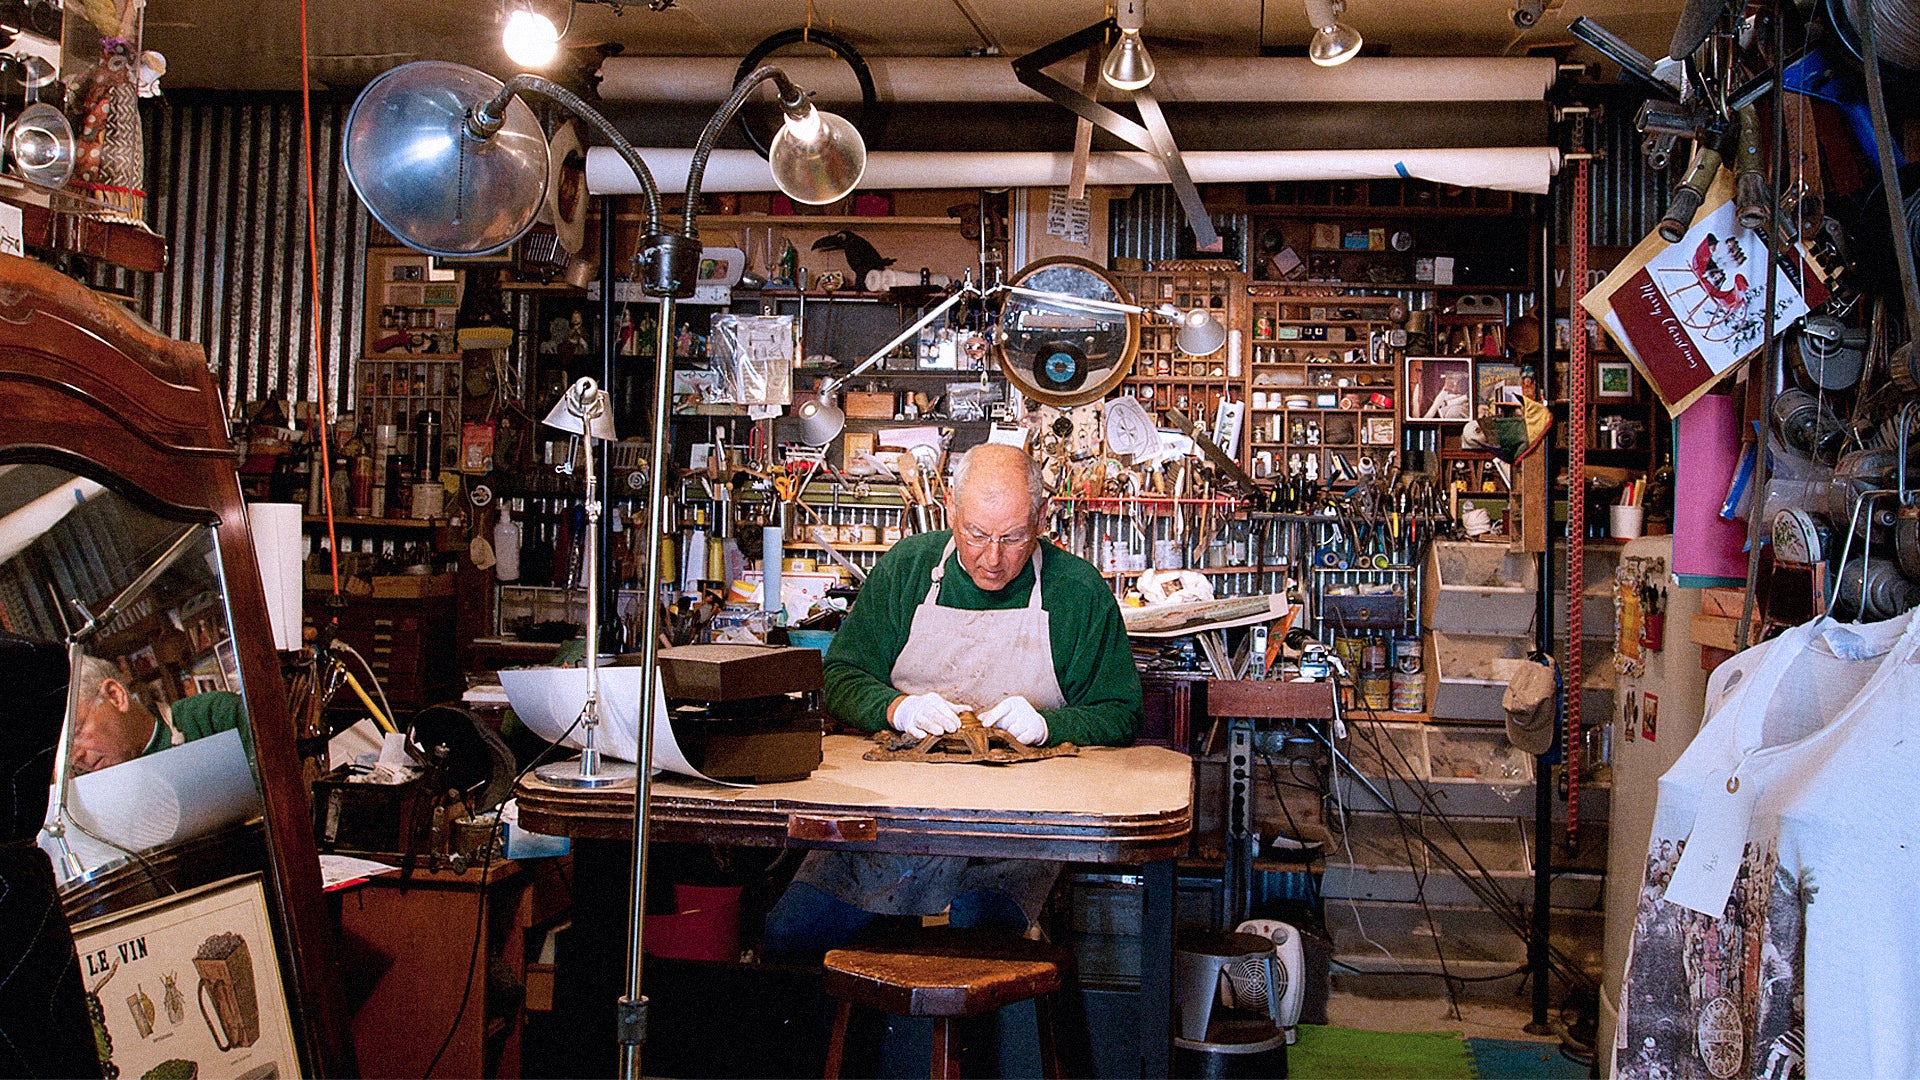
Sweden Wants To Fight Our Disposable Culture With Tax Breaks For Repairing Old Stuff - Fast Company
A proposed new law takes aim at wasteful consumerism.
The US President's new proposal to tax international students has been approved by the White House for release this week. It's an unprecedented $100,000 tax on int'l grads who stay to work after graduation on Optional Practical Training (most grads do), a crucial bridge to remaining by any channel.
Immigration fees in the US

Taxes on visas and other immigration-related fees, especially those increased or implemented in 2025–
Taxes on High-Skill Immigration: Demand and Supply Response in the International Student-OPT-Work Visa Pipeline

Exclusive | U.S. Weighs $100,000 Fee for Foreign Students Wanting to Work After Graduation

The US President's new proposal to tax international students has been approved by the White House for release this week. It's an unpreceden…
