


Here are some of the best apps and services to help keep your money on track, whether you’ve never created a budget or you’re a seasoned investor.
MetaMask: Where your money lives
Buy, trade, earn, and spend, all from one app you control.
Personal Finance
Get the Business Insider take and compare the best savings accounts, best credit cards, best insurance policies, and more. Never feel like a financial outsider again.
Manifest Financial | Banking Solutions for Creators
Crafted specifically for creators, streamlining financial management with seamless payments and effortless expense tracking—all in one place.

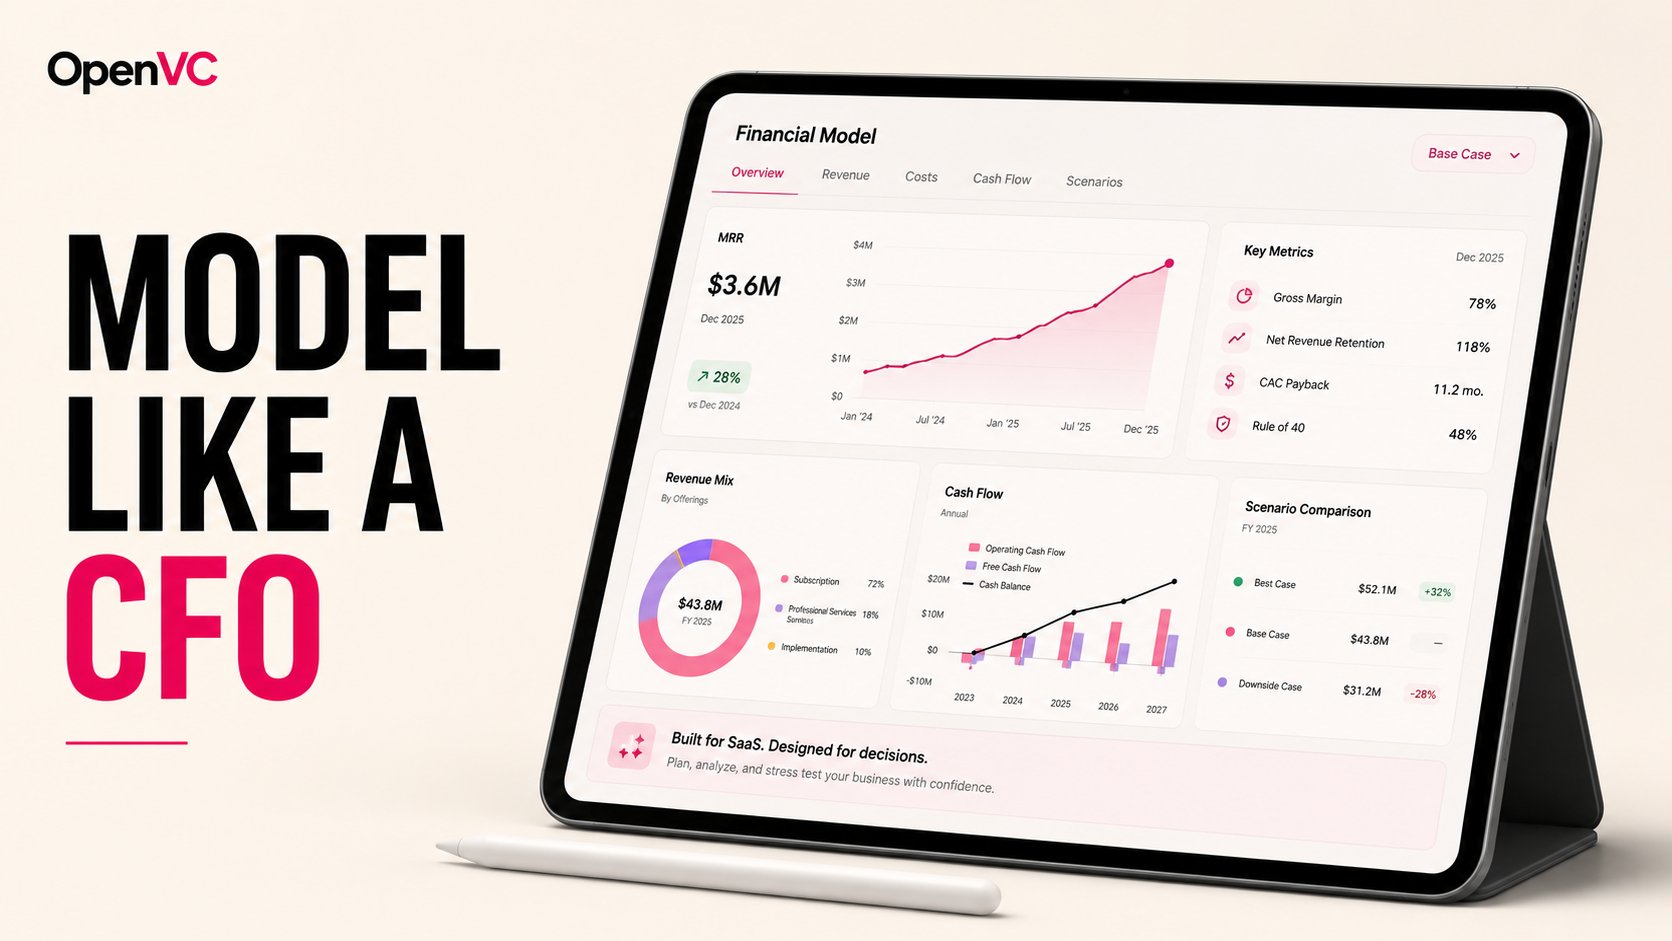
12 Best Startup Financial Model Templates [Free & Paid]
Need a financial model for your startup? Fear not. I have extensively compared the top 12 templates, free and paid, so you don't have to do it.
Cash versus Debit Card: The Role of Budget Control
Due to the financial crisis, an increasing number of households face financial problems. This may lead to an increasing need for monitoring spending and budgets. We demonstrate that both cash and the debit card are perceived as helpful in this respect. We show that, on average, consumers responsible for financial decision making within a household find cash and the debit card equally helpful for monitoring their household finances. Individuals differ in major respects, however. In particular, low earners and the liquidity‐constrained prefer cash as a budgeting tool. Finally, we present evidence that at an aggregated level, such preferences strongly affect consumer payment behavior. These findings suggest that the substitution of cash by cards may slow down because of the financial crisis.

AppSignal — Error Tracking & Performance Monitoring
Error tracking and performance monitoring for Ruby, Elixir, Node.js, and Python developers. One install, one bill — free for 50K requests/mo, no credit card.
Fi Money rolls out AI feature for users' queries on personal finance via ChatGPT, Gemini- Moneycontrol.com
Until now, users relied on generic prompts and manual inputs to use AI tools for financial advice, Fi has replaced this with a structured, consent-driven way to share real financial data, the neo-banking firm's co-founder Sumit Gwalani has said
Temporal Reframing and Participation in a Savings Program: A Field Experiment
This study explores whether framing savings in more or less granular formats can increase sign-ups for a recurring deposit program in a FinTech environment. , A growing number of American workers are now freelancers and thus, responsible for their own retirement savings, yet they face psychological hurdles that hamper them from saving enough money for the long term. Although prior theory-derived interventions have been successful in addressing some of these obstacles, encouraging participation in saving programs is a challenging endeavor for policy makers and consumers alike. In a field setting, we test whether framing savings in more or less granular formats (for example, saving daily versus monthly) can encourage continued saving behavior through increasing the take up of a recurring deposit program. Among thousands of new users of a financial technology app, we find that framing deposits in daily amounts as opposed to monthly amounts quadruples the number of consumers who enroll. Furthermore, framing deposits in more granular terms reduced the participation gap between lower- and higher-income consumers: three times as many consumers in the highest rather than lowest income bracket participated in the program when it was framed as a $150 monthly deposit, but this difference in participation was eliminated when deposits were framed as $5 per day.

Bare the wealth
A Linux programmer builds a "wealth monitor" that tracks Red Hat's valuation and who's getting rich off free software.
The Future of Money: How the Digital Revolution Is Tran…
A cutting-edge look at how accelerating financial chang…

FinTech Adoption Across Generations: Financial Fitness in the Information Age
This paper analyzes how better access to financial information via new technology changes use of consumer credit and affects financial fitness. We exploit the introduction of a smartphone application for personal financial management as a source of exogenous variation. FinTech adoption reduces financial fee payments and penalties, but differs cross-sectionally in the population. After adopting the new technology, Millennials and members of Generation X incur fewer financial fees and penalties, whereas Baby Boomers do not benefit from the technological advance. Millennials and Gen Xers save fees by using their credit cards rather than overdrafts to manage short-term liabilities. Moreover, Millennials shift some of their spending to discretionary entertainment, whereas members of Generation X remain more austere. Finally, while men tend to adopt new technology and access information at a higher rate, the economic impact of access is larger for women.
Household Financial Transaction Data
The growth of the availability and use of detailed household financial transaction micro data has dramatically expanded the ability of researchers to understand both household decision making and aggregate economic fluctuations across a wide range of fields. This class of transaction data is derived from a myriad of sources, including financial institutions, FinTech apps, and payment intermediaries. We review how these detailed data have been utilized in finance and economics research and analyze both their benefits and limitations as compared to more traditional measures of income, spending, and wealth. Finally, we discuss the future potential of this flexible class of data in firm-focused research, real-time policy analysis, and macro statistics.

The Ostrich in Us: Selective Attention to Personal Finances
Abstract We analyze attention to personal finances using a high-frequency panel of bank data, including information on logins. We document a number of robust patterns. Relative to their personal histories, individuals pay more attention when holding more cash and liquidity and when receiving income. In contrast, attention decreases discretely as bank account balances go from positive to negative and then decreases further as overdraft debt increases. We conclude that Ostrich effects in a personal finance context, i.e., the avoidance of obtaining information on everyday personal finances, is a widespread phenomenon and explore a number of explanations for our findings.

Pretty stoked to unveil something I’ve been working on for a few months: AtmoPay - a Payment Service Provider aiming at providing creators a monetization rail on the Open Web. atmopay.birdsongapps.com
Pretty stoked to unveil something I’ve been working on for a few months: AtmoPay - a Payment Service Provider aiming at providing creators a monetization rail on the Open Web. atmopay.birdsongapps.com
