

Victorians are dealing with higher interest rates and household budgets are under pressure.
Exclusive poll shows nearly half of respondents defecting from Victorian Labor. What do these voters care about?
Victorian voters surveyed named cost of living, crime and health as their top three policy issues, with just over three months until the next state election.
Regulator reduces Victorian default electricity prices | Essential Services Commission
The Essential Services Commission has announced a reduction in Victoria’s default electricity prices to apply from 1 July 2026 to 30 June 2027.
Victoria is facing a $3b-a-year debt bomb
Australia’s most indebted state government faces a raft of fiscal challenges over the next five years after the 10-year bond rate surpassed the 6 per cent mark last week.
Economic Possibilities for our Grandchildren- John Maynard Keynes
We are suffering just now from a bad attack of economic pessimism. It is common to hear people say that the epoch of enormous economic progress which characterised the nineteenth century is over; that the rapid improvement in the standard of life is now going to slow down—at any rate in Great Britain; that a decline in prosperity is more likely than an improvement in the decade which lies ahead of us.
As Victoria tries to ease the cost of living, high-earners reap the biggest benefits
From free transport to registration rebates, the state government’s attempt to help Victorians is disproportionately benefiting those who need it the least.
Exponential Growth Bias and Household Finance
ABSTRACT Exponential growth bias is the pervasive tendency to linearize exponential functions when assessing them intuitively. We show that exponential growth bias can explain two stylized facts in household finance: the tendency to underestimate an interest rate given other loan terms, and the tendency to underestimate a future value given other investment terms. Bias matters empirically: More‐biased households borrow more, save less, favor shorter maturities, and use and benefit more from financial advice, conditional on a rich set of household characteristics. There is little evidence that our measure of exponential growth bias merely proxies for broader financial sophistication.

Household Debt: Facts, Puzzles, Theories, and Policies
Borrowing decisions affect most households, with large stakes and implications for research subfields as varied as macroeconomics and industrial organization. I review theoretical and empirical work on household debt: its prevalence, level, growth, and composition, as well as various measures of consumer choice and market (in)efficiency, elasticities, and prices, including new evidence on how borrowing heterogeneity affects the distribution of the opportunity cost of consumption. I also discuss opportunities and challenges in policy evaluation. A key takeaway is that puzzles abound, and I highlight numerous avenues for further research.

Victorian opposition pledges to toughen bail and sentencing laws
The Victorian opposition has pledged to expand the government's "adult time for violent crime" laws and introduce a "one-strike" bail rule that would see re-offenders automatically denied bail.
Guardian Essential poll: Labor’s housing and tax changes fail to win over voters as support for One Nation swells
Just 25% of Australians polled back the budget while the majority believe the government has fallen short of expectations over the past year
Political donations
Information about Victorian regulations on political donations, including obligations for donors and recipients.
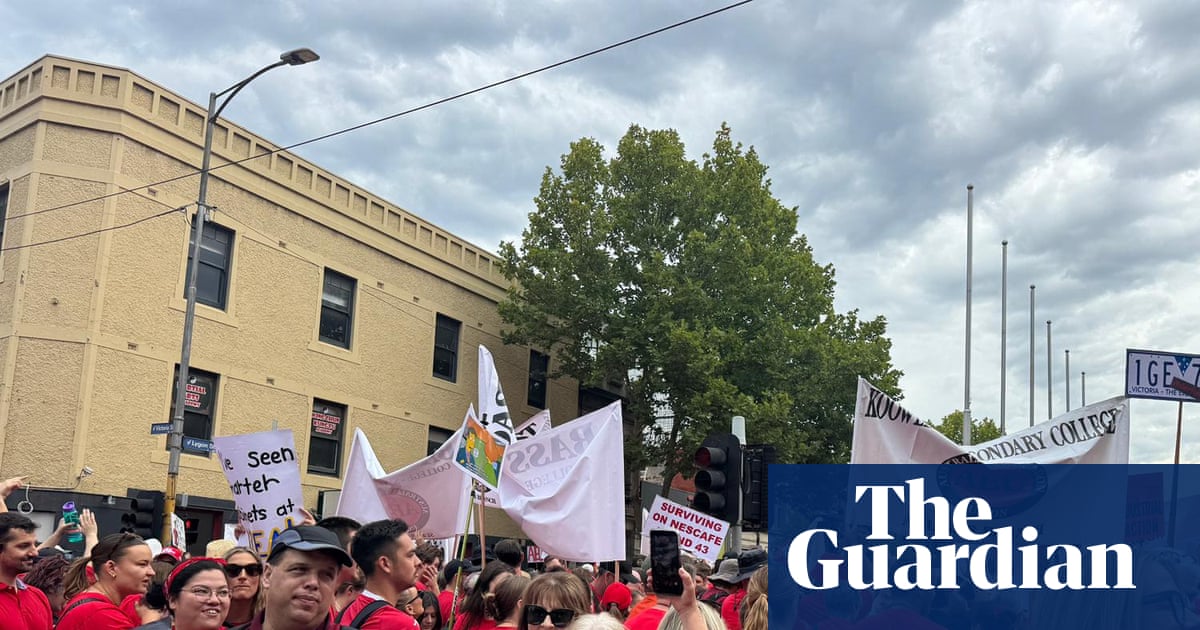
Victorian teachers are to be the best paid in Australia. A union rebellion helped seal the deal
Salaries will rise 28.3% to 32.4% over four years, an outcome partly shaped by a rank-and-file revolt within the Australian Education Union
Does Pension Automatic Enrollment Increase Debt? Evidence from a Large-Scale Natural Experiment
Does automatic enrollment into retirement saving increase household debt? We study the randomized roll-out of automatic enrollment pensions to 160,000 employers in the United Kingdom with 2-29 employees. We find that the additional savings generated through automatic enrollment are partially offset by increases in unsecured debt. Over the first 41 months after enrollment, each additional month increases the average automatically enrolled employee’s pension savings by £33-£39, unsecured debt (such as personal loans and bank overdrafts) by £7, the likelihood of having a mortgage by 0.05 percentage points, and mortgage balances by £120. Automatic enrollment causes loan defaults to fall and credit scores to rise modestly.

Liquidity versus Wealth in Household Debt Obligations: Evidence from Housing Policy in the Great Recession
We exploit variation in mortgage modifications to disentangle the impact of reducing long-term obligations with no change in short-term payments ("wealth"), and reducing short-term payments with no change in long-term obligations ("liquidity"). Using regression discontinuity and difference-in-differences research designs with administrative data measuring default and consumption, we find that principal reductions that increase wealth without affecting liquidity have no effect, while maturity extensions that increase only liquidity have large effects. This suggests that liquidity drives default and consumption decisions for borrowers in our sample and that distressed debt restructurings can be redesigned with substantial gains to borrowers, lenders, and taxpayers.
Debt Traps? Market Vendors and Moneylender Debt in India and the Philippines
A debt trap occurs when someone takes on a high-interest-rate loan and is barely able to pay back the interest, and thus perpetually finds themselves in debt (often by refinancing). Studying such practices is important for understanding financial decision-making of households in dire circumstances, and also for setting appropriate consumer protection policies. We conduct a simple experiment in three sites in which we paid off high-interest moneylender debt of individuals. Most borrowers returned to debt within six weeks. One to two years after intervention, treatment individuals were borrowing at the same rate as control households.
Victorian election polls 2026 — average and ledger — Australian Election Tracker
Victorian state election 2026 polls: sourced statewide primary votes and a transparent weighted average with uncertainty bands. Latest tracker average (as of 2026-10-10): Labor 24.5%, Coalition 29.1%, One Nation 22.6%, Greens 14.9%, Others 8.9%. Not a forecast.

Cash versus Debit Card: The Role of Budget Control
Due to the financial crisis, an increasing number of households face financial problems. This may lead to an increasing need for monitoring spending and budgets. We demonstrate that both cash and the debit card are perceived as helpful in this respect. We show that, on average, consumers responsible for financial decision making within a household find cash and the debit card equally helpful for monitoring their household finances. Individuals differ in major respects, however. In particular, low earners and the liquidity‐constrained prefer cash as a budgeting tool. Finally, we present evidence that at an aggregated level, such preferences strongly affect consumer payment behavior. These findings suggest that the substitution of cash by cards may slow down because of the financial crisis.
